Volume-Weighted Average Price (VWAP)
What is VWAP?
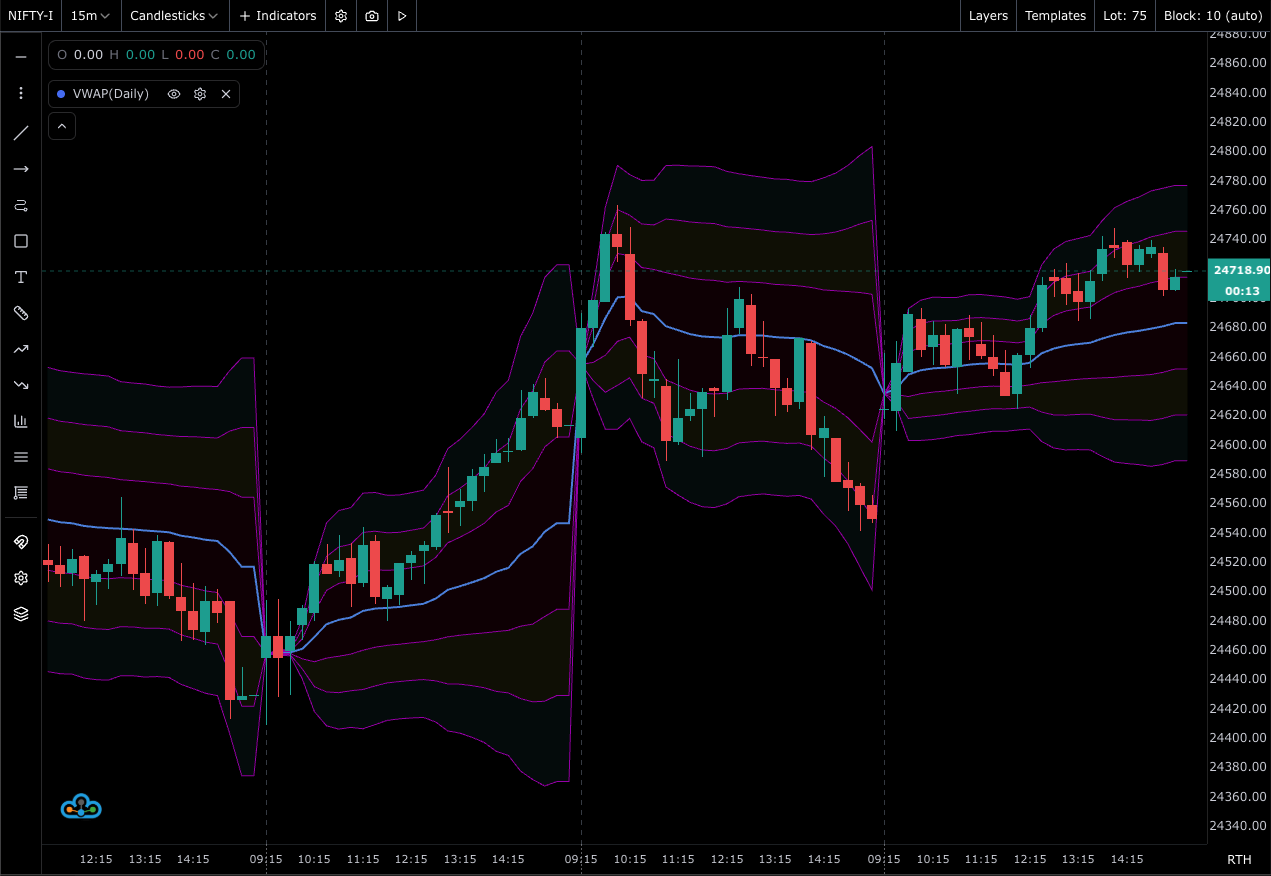
VWAP represents the average price of an asset weighted by traded volume over a session or defined window. It provides a fair-value benchmark used by institutions and retail traders alike.
How the VWAP Indicator Works
VWAP accumulates (Price × Volume) and divides by cumulative Volume over the session:
VWAP = Σ(Price × Volume) / Σ(Volume)
Interpretation:
- Above VWAP: Bullish intraday bias; Below VWAP: Bearish bias.
- VWAP can act as dynamic support/resistance.
Available Settings in FutPrint
- Session Reset: Daily/session-based (default)
- Bands (optional): Standard deviations around VWAP (if enabled)
- Style: Line color, thickness; band colors
Practical Usage and Best Practices
- Use as a fairness reference for entries/exits.
- Combine with higher-timeframe levels for confluence.
- In mean-reverting contexts, look for reversion to VWAP after extensions.
Limitations:
- During strong trends, price may remain far from VWAP; avoid countertrend trades without confirmation.
Using VWAP in the Platform
- Add VWAP from Trend & Directional indicators.
- Configure session handling and optional deviation bands.
- Customize visual styles.